Electronic Invoicing: understanding E-Reporting
The French electronic invoicing reform requires companies established in France and subject to VAT to comply with two reporting mechanisms: e-invoicing and e-reporting.
To meet these requirements, companies must use an Accredited Platform (Plateforme Agréée – PA), which is responsible for transmitting the required data to the French Tax Administration (DGFiP).
While e-invoicing applies to electronic invoices exchanged between companies established in France and subject to VAT, e-reporting covers transactions that fall outside this scope. It enables businesses to transmit to the French Tax Administration data relating to certain commercial transactions and payment collections that are not covered by the e-invoicing framework.

Sommaire
- 1. E-reporting data flows
- 2. E-reporting of transaction and payment data
- 3. International B2B transactions
- 4. B2C transactions
- 5. Autres opérations entrant dans le champ du e-reporting
- 6. Les périodicités de transmission des données de transaction et de paiement
- 7. Secure your e-reporting flows with Orchestrade eFacture
1. E-reporting data flows
As part of the e-reporting requirements, companies must transmit several types of data to the French Tax Administration depending on the nature of the transactions concerned: international B2B transactions and/or B2C transactions (transactions with individuals and associations not subject to VAT). Payment data must also be reported to the French Tax Administration.
These transmissions rely on several standardized data flows (Flow 10), making it possible to distinguish invoice data from payment data and consolidated reporting.
- Flow 10.1: Transmission of international B2B invoice data
- Flow 10.2: Transmission of payment data relating to international B2B invoices
For reporting collections relating to invoices declared through Flow 10.1 - Flow 10.3: Transmission of consolidated transaction data for B2C transactions and associations not subject to VAT
- Flow 10.4: Transmission of consolidated payment data for B2C transactions and associations not subject to VAT
For reporting collections relating to transactions declared through Flow 10.3
Summary Table of Flow 10 Reporting
| B2Bi | B2C / Associations not subject to VAT | |
|---|---|---|
| Transaction | Flow 10.1 | Flow 10.3 |
| Payment | Flow 10.2 | Flow 10.4 |
2. E-reporting of transaction and payment data
A. Who is subject to e-reporting ?
Companies subject to the e-reporting requirements are businesses subject to VAT in France that carry out transactions with individuals, associations not subject to VAT, and/or foreign companies as part of international B2B transactions.
This mechanism applies to the transmission to the French Tax Administration (DGFiP) of data relating to certain transactions that fall outside the scope of e-invoicing.
E-reporting therefore complements e-invoicing and applies to the companies concerned according to the same implementation timetable as the obligation to issue electronic invoices.
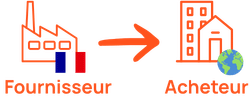
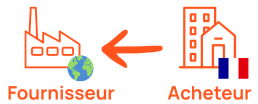
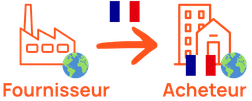
Diagram 1 : “Scope of application for international B2B transactions”
- When the supplier is subject to VAT and established in France, but the buyer is located abroad (within or outside the EU).
- When a buyer subject to VAT and established in France purchases goods or services from a foreign supplier (excluding imports of goods).
- When a foreign supplier and a foreign customer carry out transactions that are taxable in France (within or outside the EU).
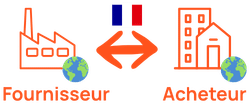
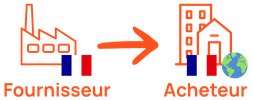
Diagram 2 : “Scope of application for B2C”
- When the supplier is subject to VAT and established in France, and the buyer is not subject to VAT (whether located in France, elsewhere in the EU, or outside the EU).
- When the supplier is established abroad (and is not registered under the EU One-Stop Shop scheme) and carries out transactions subject to VAT in France with a buyer who is not subject to VAT (whether located in France, elsewhere in the EU, or outside the EU).
B. What is transaction e-reporting ?
A company established in France and subject to French VAT is required to transmit transaction data to the French Tax Administration as part of e-reporting when it carries out transactions with individuals (B2C), associations not subject to VAT, and/or companies established abroad (international B2B).
C. What is payment e-reporting ?
When a company carries out transactions for which VAT becomes due upon receipt of payment, particularly the provision of services and advance payments, it must transmit the corresponding payment collection data to the French Tax Administration in order to report the VAT actually collected.
D. How is e-reporting data prepared?
Companies must transmit commercial transaction data to the PPF (Public Invoicing Portal) through their Accredited Platform (PA). This can be done:
- directly through an Accredited Platform (PA)
- through a Compatible Solution (SC), which prepares the transaction and/or payment data file before transmitting it to a PA
- through an ERP system or point-of-sale (POS) software for B2C transactions, with the generation of a Z report (a summary of sales recorded over a given period), which is then transmitted to a PA.
However, the transmission of this data is based on specific triggering events defined by the French Tax Administration.
The triggering events for the transmission of transaction data are :
- the invoice issue date, where the transaction has resulted in the issuance of an invoice
- the date on which the transaction takes place.
Payment data relating to the provision of services must, in turn, be transmitted on the date the payment for the transaction is collected (or for the invoice, where applicable).* This requirement applies regardless of the payment method used, except in specific cases provided for under French tax doctrine, particularly where payment is made by bank cheque.**
* VAT becomes due upon delivery of the cheque – BOI-TVA-BASE-20-20.
** Special case: where payment is made by cheque, French tax doctrine considers VAT to become due as soon as the cheque is handed over to the supplier.
Penalties may apply in particular in the event of failure to transmit the required data, late transmission, or the transmission of inaccurate data.
Read our article on penalties for more informations.
3. International B2B transactions
A. E-reporting data to be transmitted for international B2B transactions (Flows 10.1 and 10.2)
a) Buyer : e-reporting for purchases (invoice data) – Flow 10.1
Purchase e-reporting covers intra-Community acquisitions of goods, as well as services purchased from foreign suppliers, whether they are established within or outside the European Union.
Imports of goods from non-EU countries are excluded from the e-reporting requirements, as these transactions are already covered by customs procedures.
Invoice data is transmitted in a detailed format (Flow 10.1). However, as part of the simplification measures introduced by Article 123 of the 2026 Finance Act, only invoice header and footer data are required. Invoice line-item data is therefore not transmitted as part of purchase e-reporting.
Finally, unlike sales flows, there is no payment e-reporting requirement for purchases. The French Tax Administration does not require payment data for international purchases, as the reporting requirement focuses primarily on the transaction itself and, where applicable, the reverse charge of VAT.
b) Supplier : e-reporting for sales (invoice data) – Flow 10.1
Sales e-reporting applies to transactions carried out with foreign business customers, whether they are established within or outside the European Union.
Invoice data is transmitted in the detailed Flow 10.1 format.
For transactions carried out with taxable persons, the required information corresponds to the data required for domestic B2B invoices, except that the buyer’s SIREN number is replaced by :
- the customer’s VAT identification number when the customer is established within the EU
- for customers established outside the EU, an identifier composed as follows: country code + first 16 characters of the company name
For transactions carried out with non-taxable persons, the invoice data to be transmitted includes:
- The SIREN number of the supplier of the goods or services
- The reporting period, or, for transactions involving an electronic invoice, the invoice date
- The statement “VAT accounted for on the basis of debits”, where applicable
- The transaction category:
- Supplies of goods subject to VAT
- Supplies of services subject to VAT
- Supplies of goods and services carried out by taxable persons established in France where the place of supply is outside France
- Transactions subject to the schemes provided for under Article 266(1)(e), Article 268 and Article 297 A of the French General Tax Code (CGI)
- For each VAT rate, the total amount excluding VAT and the corresponding VAT amount
- The total amount of VAT due in France. For transactions denominated in a foreign currency, this amount must be expressed in euros
- The currency
- The transaction date
- The invoice numbers
c) Supplier: e-reporting for sales (payment data) – Flow 10.2
Payment e-reporting applies to transactions for which VAT becomes due upon receipt of payment, particularly the provision of services and advance payment invoices.
Unlike transaction e-reporting, this requirement applies only to sales transactions and does not apply to purchase flows.
Payment data is transmitted in the detailed Flow 10.2 format and includes:
- The SIREN number of the supplier of the goods or services
- The reporting period, or, for transactions involving an electronic invoice, the invoice date
- The date on which payment is actually received
- The amount received, broken down by VAT rate
- The invoice number
4. B2C transactions
A. E-reporting data to be transmitted for B2C transactions
a) Supplier: e-reporting for sales (transaction data)– Flow 10.3
For transactions carried out with individual consumers (B2C), transaction data is transmitted in the consolidated Flow 10.3 format.
Unlike the detailed flows used in certain international B2B scenarios, this format is based on the transmission of a daily aggregate of transactions, including:
- the number of transactions
- the category of transactions concerned
- the aggregated amounts broken down by VAT rate
The data transmitted includes:
- The SIREN number of the supplier of the goods or services
- The reporting period, or, for transactions involving an electronic invoice, the invoice date
- The statement “VAT accounted for on the basis of debits”, where applicable
- The transaction category:
- Supplies of goods subject to VAT
- Supplies of services subject to VAT
- Supplies of goods and services carried out by taxable persons established in France where the place of supply is outside France
- Transactions subject to the schemes provided for under Article 266(1)(e), Article 268 and Article 297 A of the French General Tax Code (CGI)
- For each VAT rate, the total amount excluding VAT and the corresponding VAT amount
- The total amount of VAT due in France. For transactions denominated in a foreign currency, this amount must be expressed in euros
- The currency
- The transaction date
b) Supplier: e-reporting for sales (payment data) – Flow 10.4
As with Flow 10.2, this requirement applies to transactions for which VAT becomes due upon receipt of payment.
The information transmitted to the French Tax Administration includes:
- The SIREN number of the supplier of the goods or services
- The reporting period, or, for transactions involving an electronic invoice, the invoice date
- The date on which payment is actually received
- The total amount received, broken down by VAT rate
5. Other transactions within the scope of e-reporting
Beyond international B2B and B2C transactions, certain transactions subject to specific VAT rules also fall within the scope of e-reporting.
This notably applies to certain transactions involving the French Overseas Departments, Regions, Communities and Territories (DROM-COM-TAAF). Depending on the territory concerned, companies subject to VAT that carry out transactions with these territories may be required to submit e-reporting rather than e-invoicing. Conversely, transactions involving Martinique, Guadeloupe and Réunion fall within the scope of e-invoicing.
Read our article on DROM-COM-TAAF territories to learn more.
These transactions must be clearly distinguished by the French Tax Administration in order to:
- identify the exact type of transaction concerned
- apply the appropriate VAT treatment
- distinguish between specific VAT regimes and exemptions.
E-reporting therefore makes it possible to determine the appropriate tax treatment for each transaction.
6. Frequency of transaction and payment data reporting
Frequency and deadlines for reporting transaction and payment data (e-reporting)
| Transmission of transaction data | Transmission of payment data | |||
|---|---|---|---|---|
| Reporting frequency | Reporting deadline | Reporting frequency | Reporting deadline | |
| Companies subject to the standard monthly VAT regime | Every 10 days 3 submissions per month: Periode 1: from the 1st to the 10th of the month Period 2: from the 11th to the 20th of the month Period 3: from the 21st to the end of the month |
10 days after the end of the reporting period, as follows: Period 1: by the 20th of the month Period 2: by the 30th of the month*¹ Period 3: by the 10th of the following month |
Monthly | By the 10th of the following month |
| Companies that have opted for the standard quaterly VAT reigme *2 | Monthly | By the 10th of the following month | ||
| Companies subject to the simplified VAT regime | Monthly | No later than between the 25th and the 30th of the following month | Monthly | No later than between the 25th and the 30th of the following month |
| Companies eligible for the VAT exemption scheme | Every 2 months | No later than between the 25th and the 30th of the reporting period | Every 2 months | No later than between the 25th and the 30th of the reporting period |
*1 Except in February ; *2 Companies that pay less than €4,000 in VAT per year
source : impots.gouv.fr
7. Secure your e-reporting flows with Orchestrade eFacture
ARTEVA, an Accredited Platform (PA) and a specialist in EDI and electronic invoicing for 20 years, supports large enterprises, mid-sized companies, and SMEs in France and internationally in the digitalization and optimization of their intercompany exchanges.
With Orchestrade eFacture, ARTEVA provides a ready-to-use invoice exchange solution designed to meet the requirements of the French Electronic Invoicing Reform while integrating seamlessly with the operational realities of multi-subsidiary and multi-system organizations.
The platform covers all regulatory and operational requirements:
- Directory management, e-invoicing, e-reporting, and invoice lifecycle management
- Full integration with your Information System
- Support for invoices outside the scope of the reform and international invoices
- OCR and data capture for supplier invoices, with approval workflows and advanced business controls
- Automation of P2P (Procure-to-Pay) and O2C (Order-to-Cash) processes
Designed for complex environments, Orchestrade eFacture provides a centralized and optimized view of all invoicing flows.


